Altcoins
Ripple Secures Final Approval to Launch U.S. National Trust Bank

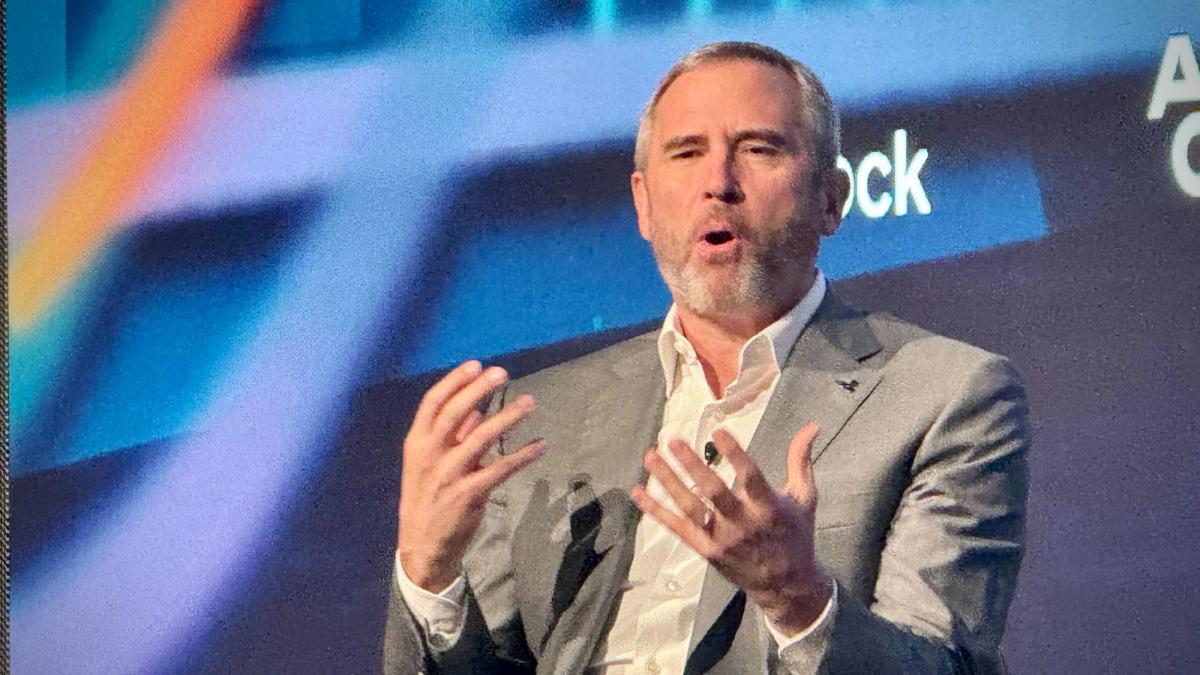
The Office of the Comptroller of the Currency has approved Ripple National Trust Bank, giving Ripple a federal charter to establish its own national trust bank in the United States, Chief Executive Officer Brad Garlinghouse announced on X.
The decision represents a significant regulatory step for Ripple, the blockchain company best known for developing payment infrastructure and for its close association with the XRP digital asset. A national trust bank charter places an institution under the supervision of the OCC, the federal agency responsible for chartering, regulating and supervising national banks and federal savings associations.
Unlike a conventional full-service commercial bank, a national trust bank generally focuses on fiduciary and custodial activities rather than taking deposits and making consumer or commercial loans. Its permitted business depends on the terms of its charter and the conditions imposed by regulators. The structure can be used to provide services such as asset custody, trust administration and other activities authorized under federal banking law.
For Ripple, the approval could provide a regulated banking framework for parts of its digital-asset operations. The company has spent years developing products aimed at financial institutions and cross-border payments, while the broader cryptocurrency industry has increasingly sought access to federally supervised banking and custody services. A national charter may help Ripple coordinate those activities through an entity operating within a clearly defined federal regulatory structure.
The announcement, however, did not provide details about when Ripple National Trust Bank will begin operating, where it will be based, which services it intends to offer or whether the bank has received authorization for any particular digital-asset products. It also did not disclose the bank’s capitalization, leadership beyond the connection to Ripple, or any additional conditions attached to the OCC’s approval.
Those details matter because a federal charter is not a blanket authorization to conduct every type of banking or cryptocurrency business. National trust banks remain subject to the limits of their charters and to ongoing regulatory oversight. Depending on the activities a bank pursues, it may also need to address requirements involving risk management, cybersecurity, anti-money-laundering controls, consumer protection and the safeguarding of customer assets.
The OCC’s role is particularly important for firms operating in digital assets, an industry that has faced uncertainty over which regulators oversee different products and services. A federal charter can establish direct supervision by a national banking regulator, but it does not eliminate the need to comply with other applicable federal or state rules. It also does not resolve broader questions over how individual cryptocurrencies, payment arrangements or investment products should be classified.
Ripple’s move comes as financial and technology companies continue to explore regulated ways to offer digital-asset services. Traditional banks have expanded their work in areas such as blockchain-based settlement and custody, while cryptocurrency companies have pursued licenses and partnerships intended to connect digital networks with the established financial system. The competition has made access to compliant banking infrastructure an important strategic issue.
For Ripple, the trust-bank structure may offer greater control over services that would otherwise rely on outside custodians or banking partners. It could also strengthen the company’s ability to present its institutional offerings within a framework recognized by U.S. banking authorities. The practical impact will depend on how the bank is organized and what business it ultimately conducts.
Garlinghouse’s announcement did not include a detailed statement from the OCC, nor did it outline the regulator’s reasoning. The approval therefore marks the formal authorization of Ripple’s proposed national trust bank, while leaving operational questions to be answered as the institution moves toward launch.
The announcement also adds a new dimension to Ripple’s regulatory profile. The company has been involved in a long-running legal dispute with the U.S. Securities and Exchange Commission over the sale and classification of XRP, a case that has drawn broad attention across the cryptocurrency sector. The OCC charter is a separate regulatory matter and does not, on its own, determine the legal status of XRP or settle issues under securities law.
The creation of Ripple National Trust Bank will now be watched for signs of how Ripple intends to use the charter. Its eventual activities, customer base and relationship with Ripple’s existing businesses will determine whether the approval becomes mainly a custody and fiduciary arrangement or a broader component of the company’s payments and digital-asset strategy. For now, the OCC’s decision gives Ripple the federal banking authorization it sought and places the proposed institution on a path toward operation under national trust-bank supervision.
Crypto Law Developments for the Week of October 25, 2026
Ripple Secures Final Approval to Launch U.S. National Trust Bank
South Korea’s Crypto Tax May Face Fourth Postponement Before 2029 Start: Report

Gaming Technologies of the New Time!

Calls for Enhanced Discussion on Bitcoin as Brazil’s Reserve Asset: A Move Towards ‘Internet’s Gold’

Bitcoin Declines Below $80K: deVere CEO Nigel Green Remains Bullish on Long-Term Outlook Following Strategic U.S. Bitcoin Reserve Announcement
-
 Press Releases2 years ago
Gaming Technologies of the New Time!
-
 Altcoins2 years ago
Calls for Enhanced Discussion on Bitcoin as Brazil’s Reserve Asset: A Move Towards ‘Internet’s Gold’
-
 Altcoins2 years ago
Bitcoin Declines Below $80K: deVere CEO Nigel Green Remains Bullish on Long-Term Outlook Following Strategic U.S. Bitcoin Reserve Announcement
-
 Bitcoin1 year ago
Peter Schiff เตือนนักลงทุนคริปโตขาย Ethereum (ETH) เพื่อซื้อ Bitcoin ชี้ ETH มีศักยภาพจำกัด
-
 Bitcoin2 years ago
Bitcoin Surges Past $64K as SEI and POPCAT Lead Daily Crypto Gains on September 25
-
 Bitcoin1 year ago
Strategy ขยายการถือครองบิตคอยน์สู่ 580,955 BTC หลังจากการซื้อใหม่มูลค่าหลายล้านดอลลาร์
-
 Press Releases2 years ago
Evo Exchange: Redefining the Decentralized Exchange Landscape
-
 Altcoins2 years ago
FBI เชื่อมโยงนักแสดงเกาหลีเข้ากับการแฮ็ก DMM Exchange มูลค่า 308 ล้านดอลลาร์